One Tariff Code Change Saved This Company (Yakult) 20% in Import Duty and Halved Its Imported Sales Tax — Here's How They Fought Back
Published: 07 Aug 2026
23 June 2026
The Malaysian High Court has ruled in favour of Yakult (Malaysia) Sdn. Bhd., setting aside the Royal Malaysian Customs Department's (RMCD) decision to reclassify Yakult Ace and Yakult Ace Light as beverages instead of fermented milk products.
The decision is significant as it reaffirms that tariff classification must be based on a product's essential character, rather than merely its physical form or the fact that it is sold as a ready-to-drink product.
Background
For more than 20 years, Yakult's products “Yakult Ace” and “Yakult Ace Light” had been classified under Tariff Code 0403.90.9000 as "other fermented or acidified milk".
However, in 2023, Customs reclassified the products under Tariff Code 2202.99.5000 as "other non-aerated beverages ready for immediate consumption without dilution."
The reclassification had significant tax implications:
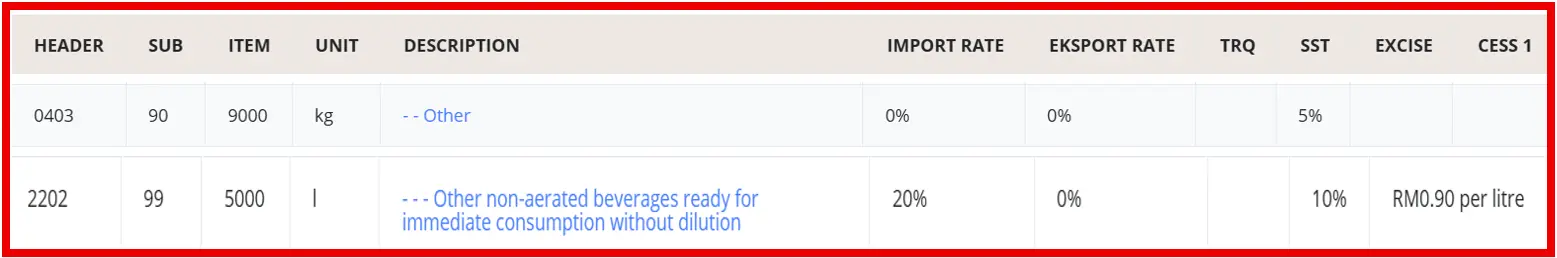
| Classification | Import Duty | Sales Tax |
|---|---|---|
| Fermented milk (HS 0403.90.9000) | 0% | 5% |
| Beverage (HS 2202.99.5000) | 20% | 10% |
Reference: JKDM HS Explorer (Official Tariff Database)
To illustrate the tax impact of the tariff reclassification, the screenshot below is extracted from the JKDM HS Explorer, the official tariff database maintained by the Royal Malaysian Customs Department (RMCD). It shows the applicable HS codes, import duty rates and import sales tax rates, supporting the comparison discussed in this article.
As a result, Yakult commenced judicial review proceedings to challenge Customs' decision.
High Court's Decision
The High Court allowed Yakult's judicial review application and quashed Customs' reclassification.
High Court judge Wan Fadhillah Nor Wan Idris held that Yakult Ace and Yakult Ace Light should remain classified as fermented milk products under Tariff Code 0403.90.9000.
The Court observed that although the products contain added water and are consumed as ready-to-drink beverages, their essential character remains that of fermented milk containing live probiotic bacteria.
The Court further noted that consumers generally associate Yakult with a probiotic fermented milk product intended to promote gut health, rather than an ordinary beverage consumed merely to quench thirst. Therefore, the addition of water does not alter the essential character of the products.
Why This Case Matters
Beyond Yakult, this judgment provides important guidance on customs tariff classification in Malaysia.
The High Court reaffirmed that:
- tariff classification should follow the General Rules for the Interpretation (GRI) of the Harmonized System;
- products should be classified according to their essential character, taking into account their composition, function and intended use;
- a ready-to-drink form does not automatically make a product a "beverage" for customs purposes; and
- Customs should have proper justification before departing from a long-standing tariff classification that businesses have relied upon for many years.
Why This Matters
This case is a timely reminder that the correct tariff classification can have a significant impact on import duty and sales tax costs. A different tariff code may result in substantially higher taxes, even though the product itself has not changed.
Businesses should not assume that a tariff classification will always remain the same. If Customs reclassifies a product, importers should carefully review the basis of the decision and assess whether it is consistent with the Harmonized System (HS) classification rules.
Where appropriate, businesses may consider seeking professional advice or challenging the classification if there are valid legal grounds to do so.
Not Sure Your Tariff Codes Would Survive a Challenge?
Contact us today to discuss how we can support your tariff classification and customs compliance in Malaysia.